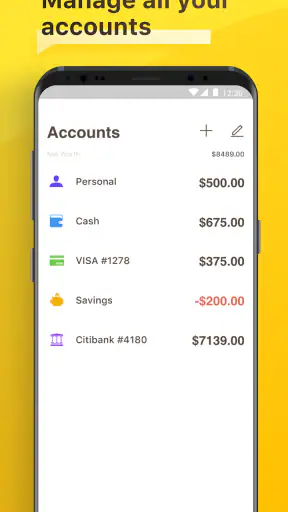
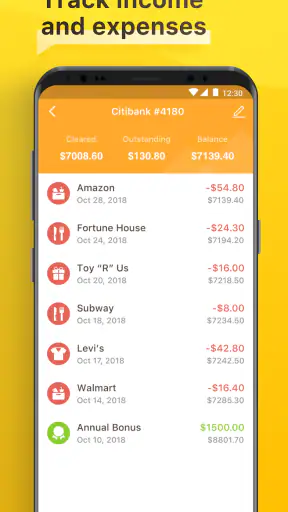
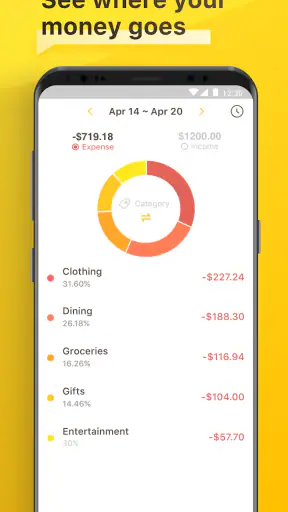
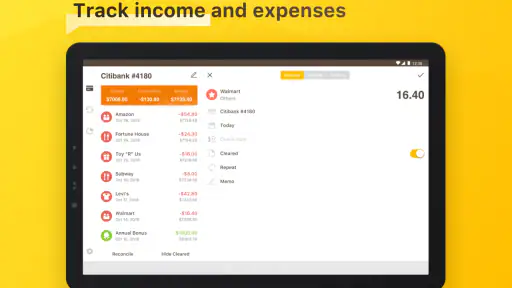
I approached Checkbook - Account Tracker as a practical question rather than a novelty: can a simple digital register make everyday money tracking easier than a paper checkbook, a notes app, or a full budgeting service? After using it in that spirit, my answer is yes for a particular kind of user. It is focused, uncomplicated, and built around recording account activity without trying to become an all-purpose financial dashboard.
That focus is both its best quality and its main limitation. If you want a lightweight place to enter deposits, withdrawals, and adjustments manually, this Finance app feels more approachable than a large budgeting platform. If you expect automatic bank connections, investment tracking, bill negotiation, or detailed spending analytics, you should look elsewhere. The important decision is not whether it has the longest feature list. It is whether you prefer a clear digital register over a more automated financial system.
What I looked for before trusting it with daily transactions
My first test was speed. A checkbook replacement only helps if recording a purchase takes less effort than ignoring it. I paid attention to whether the app’s design encouraged a simple habit: open the register, enter the transaction, check the running balance, and move on. That workflow is more important here than colorful charts or a long list of financial categories.
I also considered how well the app suits people who still use checking accounts actively, including anyone who wants to reconcile their own records with a bank statement. A manual register can be valuable because it shows the balance after transactions you have made, even when a bank’s displayed balance does not yet reflect pending activity. That makes personal discipline part of the experience, not an optional extra.
Another decision point is how much setup you are willing to accept. Large finance apps often ask you to connect accounts, classify historical spending, and learn several screens before they become useful. This app’s appeal is different: it is intended to get out of the way. I found that especially relevant for someone replacing a paper register, because the mental model remains familiar rather than forcing a new budgeting method.
There is also a privacy and control trade-off worth thinking about. Manual entry means you retain responsibility for the record, but it also means the app cannot magically correct an omitted transaction. I would not choose it casually if I knew I rarely record purchases. The system works best when the user treats it as a ledger, not as an automatic account monitor.
A realistic everyday routine
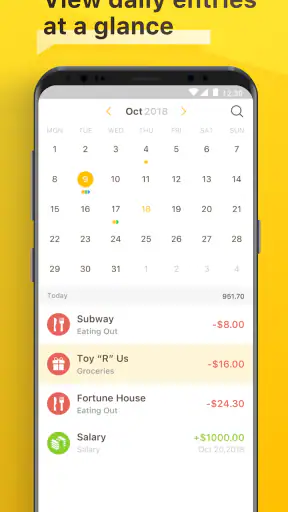
Imagine using a debit account for groceries, fuel, a subscription, and occasional cash withdrawals. With a paper checkbook, you would write each item down and subtract it from the balance. In this app, I would enter the transaction soon after paying, add enough detail to recognize it later, and use the updated balance as my working figure. At the end of the week, I would compare the register with the bank account and investigate anything that did not match.
That routine reveals an understated strength: the app can help make small purchases visible before they accumulate. It is not analyzing your behavior for you, but it gives you a place where the behavior becomes concrete. For someone who tends to check a bank balance without remembering what has already been spent, that distinction can prevent avoidable surprises.
My practical tip is to record transactions at the same moment each day rather than waiting for the end of the month. A manual tracker becomes unreliable through several tiny omissions, not usually one dramatic mistake. A short daily habit also makes reconciliation less intimidating because you are checking a small number of entries instead of reconstructing an entire period from memory.
Why its narrow purpose works
The clearest advantage is that the concept is easy to understand. TinyWork Apps has kept the product centered on the familiar checkbook-register idea, and that gives it a lower learning curve than many modern finance tools. I did not need to think in terms of elaborate budgets before I could use the basic ledger.
That simplicity is useful for people who want to track one account manually, older users who prefer a register-like workflow, or anyone who finds full personal-finance suites distracting. It can also suit a household where one person maintains the checkbook and wants a straightforward shared routine, provided everyone agrees on who records transactions and when.
A second strength is the running-balance mindset. Many notes apps can store a list of purchases, but they do not naturally encourage you to maintain an account total after every entry. A spreadsheet can do more, yet it asks you to build or maintain formulas and formatting. This app sits between those choices: more structured than notes, less demanding than designing your own workbook.
The difference matters when you are trying to answer a specific question: “What should my usable balance be after the payments I have made?” A general banking app may show the institution’s current figures, while a personal register can reflect your own record of checks, cash, and pending expenses. That is not a replacement for checking the bank, but it is a useful second view.
Its age is also part of the story. The app was released on July 24, 2015, and the current version is 2.1.2. I would not judge it by the standards of a constantly redesigned financial platform. Its value comes from the stable, old-fashioned register concept, although users who expect a polished modern ecosystem may notice the difference in approach.
Small habits that make the register more dependable
One useful workflow is to begin with the balance you actually want to monitor, then enter transactions consistently from that starting point. Mixing a bank’s available balance with your own manually adjusted figure is an easy way to create confusion. I recommend choosing one reference balance and treating every subsequent entry as part of the same record.
Another tip is to use recognizable descriptions instead of vague labels. “Store” may be enough on the day of purchase, but “weekly groceries” or the name of a recurring service is more helpful when you review the register later. The point is not to create a perfect accounting archive; it is to make old entries understandable without relying on memory.
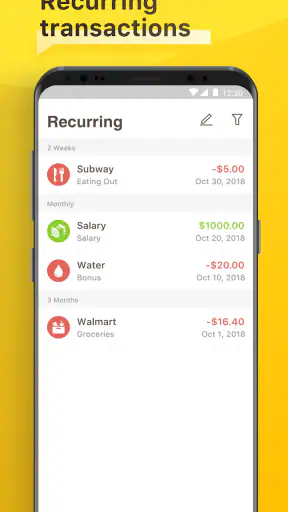
For recurring payments, I would still verify the actual charge rather than assuming every month is identical. A register is useful precisely because it records what happened, while a remembered routine can hide a changed amount or an unexpected withdrawal. This is one of the trade-offs of manual control: it encourages awareness, but it cannot replace checking the source transaction.
I would also use a regular reconciliation checkpoint. Compare the app’s entries with your bank statement, mark the items you recognize, and correct the first discrepancy you find. Do not wait until the total looks dramatically wrong. Small errors are easier to locate when the register is recent and the transaction history is still familiar.
Where other finance tools may fit better
The alternatives divide into a few broad groups. A bank’s own app is better when your priority is seeing institution-supplied balances and transactions with minimal manual work. A spreadsheet is better when you want custom formulas, long-term reporting, multiple account models, or complete control over layout. A full budgeting service is better when you want categories, targets, household planning, and broader financial analysis.
Checkbook - Account Tracker is the better fit when the central problem is maintaining a register, not building a complete financial plan. I would choose it over a notes app because the register concept gives the entries a financial purpose. I would choose it over a spreadsheet when I wanted less maintenance. But I would not choose it over a connected banking tool if automatic updates were essential to my routine.
This distinction also helps avoid a common disappointment. A manual register can show that you entered a transaction; it cannot independently prove that the transaction cleared, that the amount was correct, or that another account was not affected. If your finances are spread across several accounts, cards, loans, and investments, a single-register approach may become too narrow.
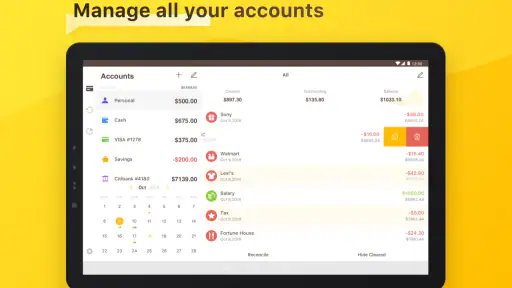
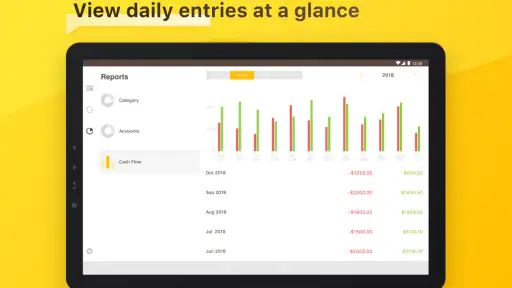
People who need detailed category reports should think carefully before switching. The app may be perfectly adequate for knowing the balance and reviewing entries, but that is not the same as answering questions such as how much was spent on dining over several months or how a household’s categories compare. A more specialized budgeting product will usually be the stronger choice for those decisions.
The real cost of moving from paper or another app
The financial entry point is friendly: the app is free, although it includes optional in-app purchases ranging from $0.99 to $19.99 per item. That makes it easy to try the core workflow before deciding whether it deserves a permanent place in your routine. I would still examine which functions matter to me before paying for anything, because the value depends on whether the register itself solves my problem.
The larger cost is not money; it is migration and consistency. Moving from paper means deciding what opening balance to use and whether to bring over old entries. Moving from a notes app means translating an unstructured list into a consistent register. Moving from a connected finance service means accepting that future entries may need to be recorded manually.
My advice is to run the old and new methods side by side briefly rather than deleting the old record immediately. Enter current transactions in the app, compare the balance with your existing method, and see whether you actually remember to maintain it. This test answers a more important question than whether the interface looks pleasant: can you sustain the habit?
For a household, agree on a single source of truth. If two people record the same purchase, the balance can be distorted; if each assumes the other will enter it, the omission is just as damaging. A simple rule—one person records shared activity, while the other reports purchases promptly—can make a manual system much more reliable.
Who should use it, and who should skip it
I would recommend it to someone replacing a paper checkbook, monitoring a primary checking account, or wanting a deliberately simple record of spending. It is also worth considering if you dislike the complexity of large financial apps and prefer to decide for yourself which transactions matter. The Everyone content rating makes it suitable for a broad audience, while the minimum operating-system requirement is Android 7.0.
I would be more cautious for anyone who routinely forgets to enter purchases, needs automatic synchronization, or expects the app to deliver financial guidance. It is not the right choice for a user who wants a complete net-worth picture, sophisticated planning, or a hands-off record. In those cases, a bank app, spreadsheet, or broader budgeting platform may justify its extra complexity.
The public response suggests a mixed but substantial user base: it holds a 3.6 average from around 9.3 thousand ratings, with more than 4 thousand written reviews and over 100 thousand installs. I read that as a reason to set expectations realistically. The app has enough adoption to be more than an experiment, but the rating also supports my view that its straightforward approach will not satisfy everyone.
My recommendation after weighing the trade-offs
Choose this app when you want a digital checkbook register, not a complete financial command center. Its strongest quality is the discipline it encourages: enter the transaction, maintain the balance, and reconcile the record. That can be more useful than a crowded dashboard when your immediate concern is knowing what has actually been committed from one account.
I like the fact that it leaves the user in control, but I would not confuse control with automation. The app rewards regular entry and careful checking. If that sounds manageable, the free starting point makes it a sensible option to test. If manual tracking already feels like a chore, switching from paper will not automatically solve the underlying habit.
My final verdict is favorable with a clear boundary. Checkbook - Account Tracker is a practical choice for focused account tracking and a poor substitute for a full budgeting or banking ecosystem. I would recommend it to a friend who wants a simple, familiar register and is willing to maintain it. I would steer a friend seeking automatic updates, deep reports, or multi-account planning toward a different category of finance app instead.


